H1Z2Z2-K Nylon-Barrier Rodent-Resistant Solar Cable
H1Z2Z2-K 1.5 kV DC solar cable with a nylon barrier beneath the outer sheath for PV routes that need a non-metallic physical defence against rodent damage.

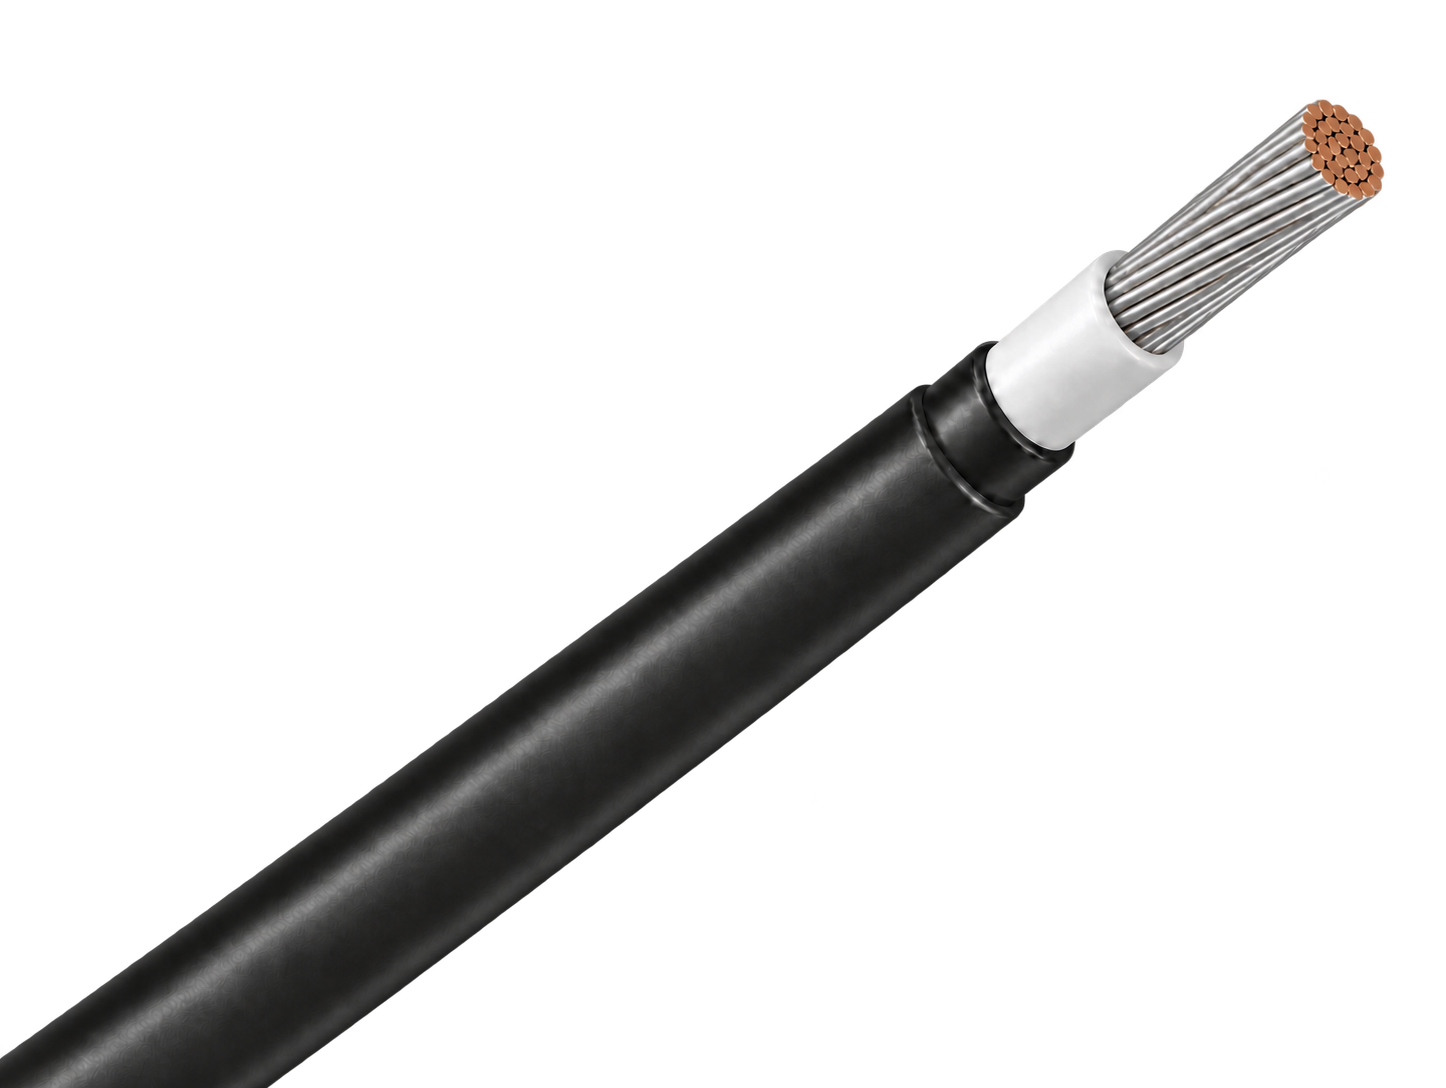
H1Z2Z2-K 1.5 kV DC solar cable with a nylon barrier beneath the outer sheath for PV routes that need a non-metallic physical defence against rodent damage.
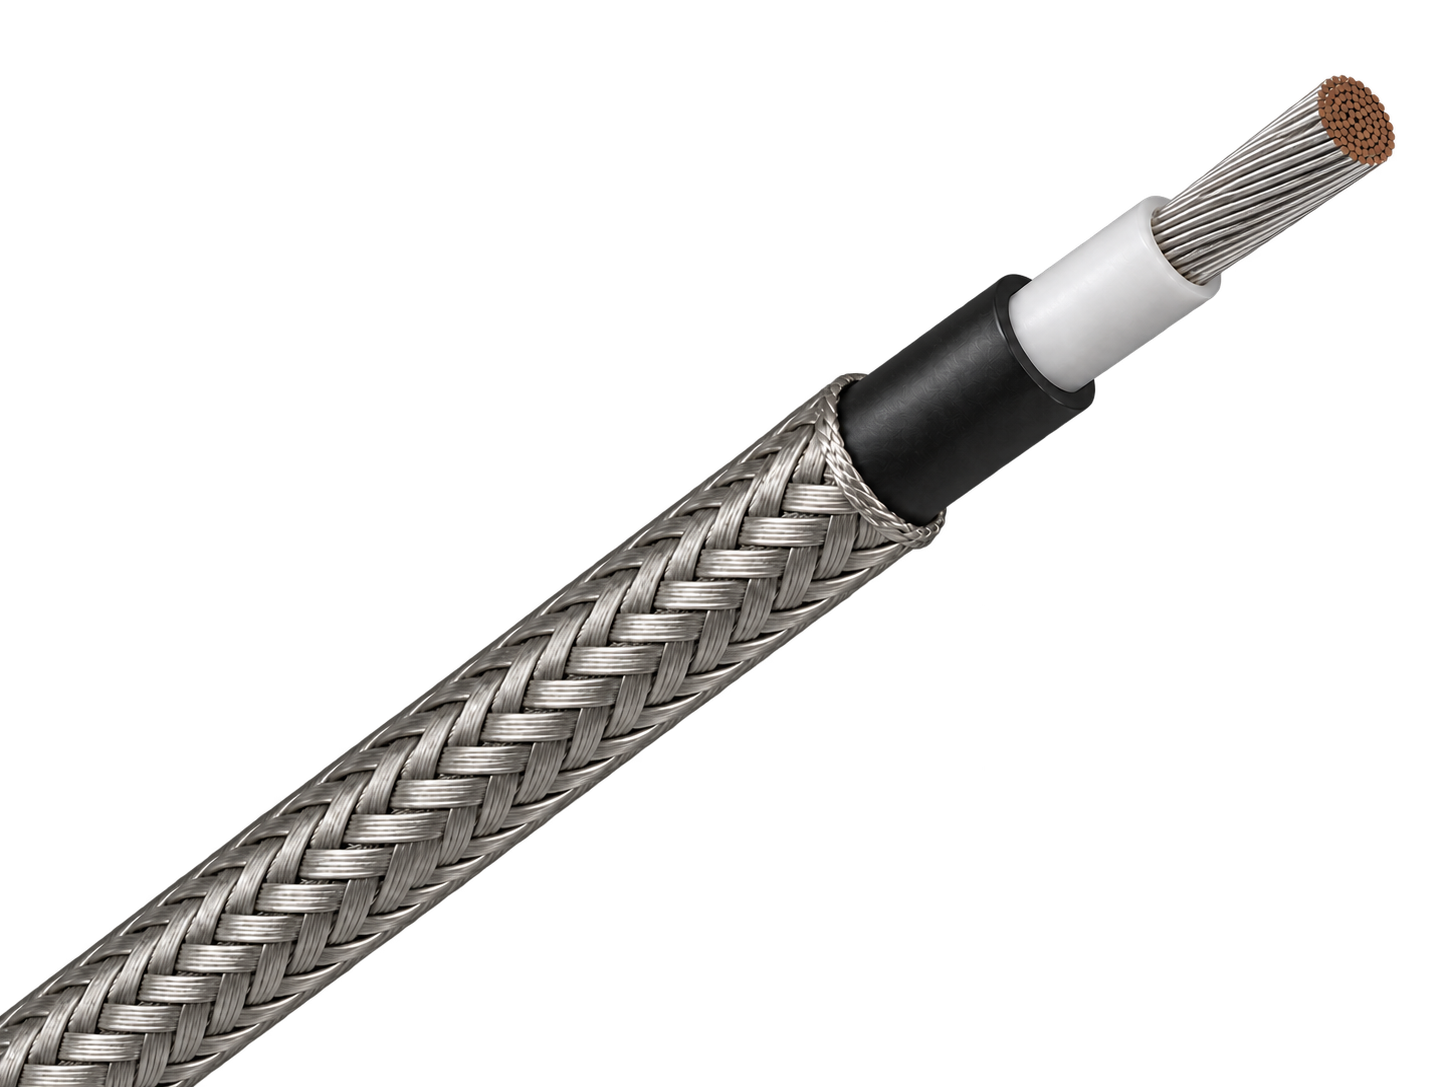
H1Z2Z2-K 1.5 kV DC solar cable with external steel-wire armour for fixed PV routes exposed to severe rodent activity or mechanical damage.
H1Z2Z2-K 1.5 kV DC solar cable with a capsaicin-based rodent-deterrent sheath for PV routes where chemical protection is preferred over added armour.
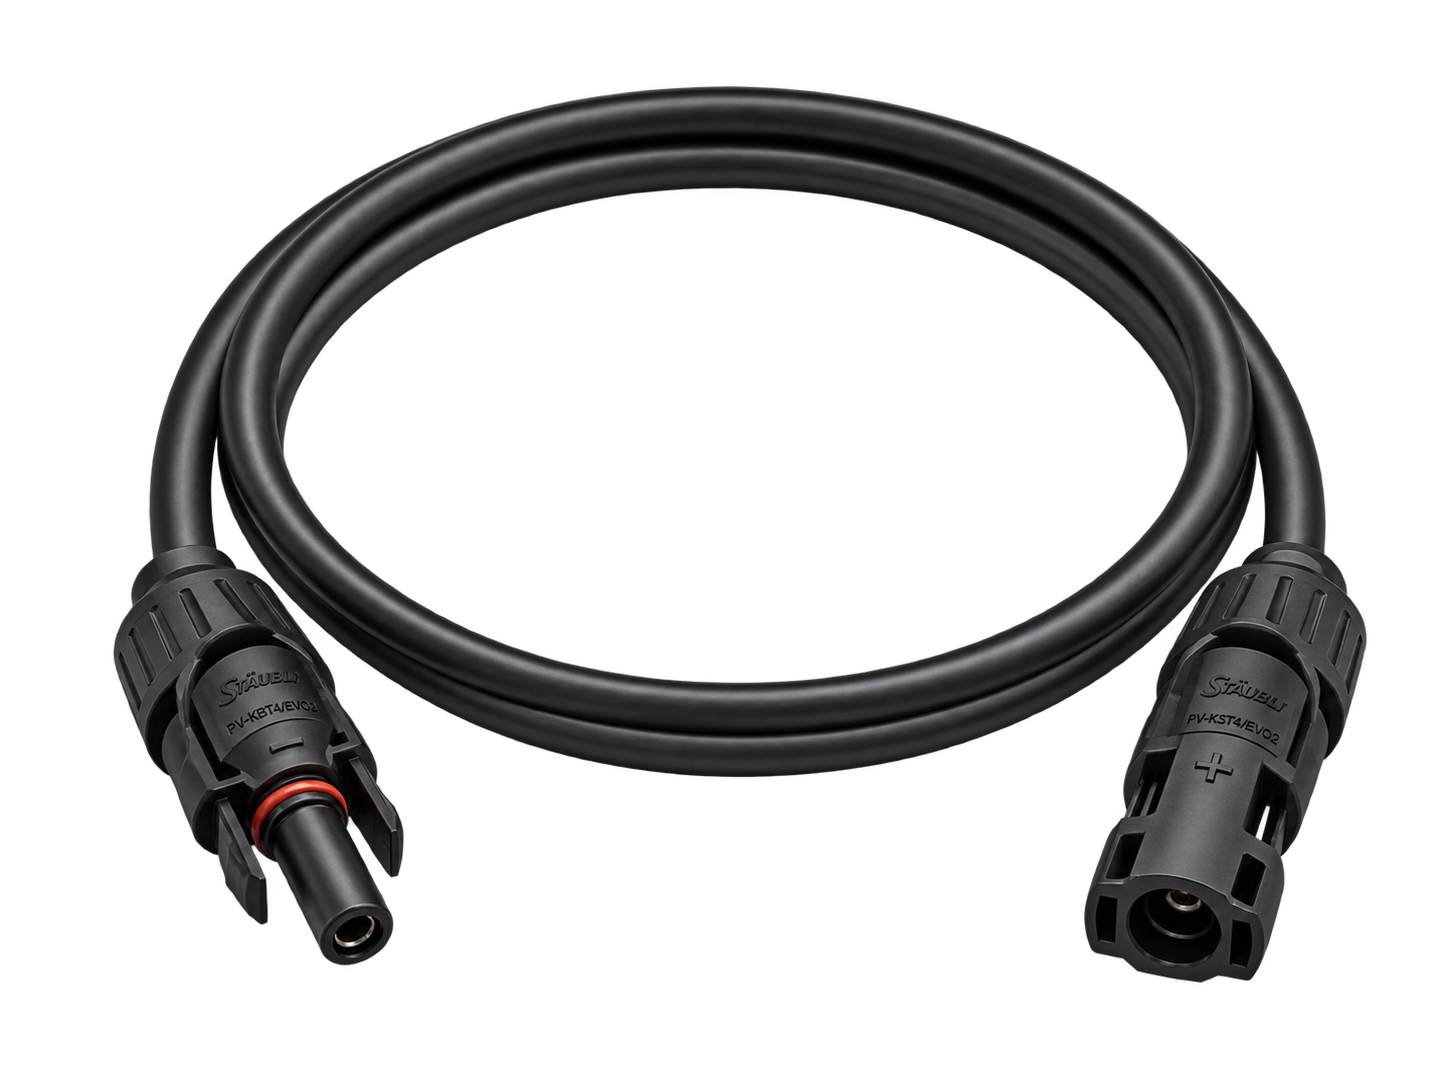
Factory-terminated PV extension cable for controlled module, string and combiner-box connections.
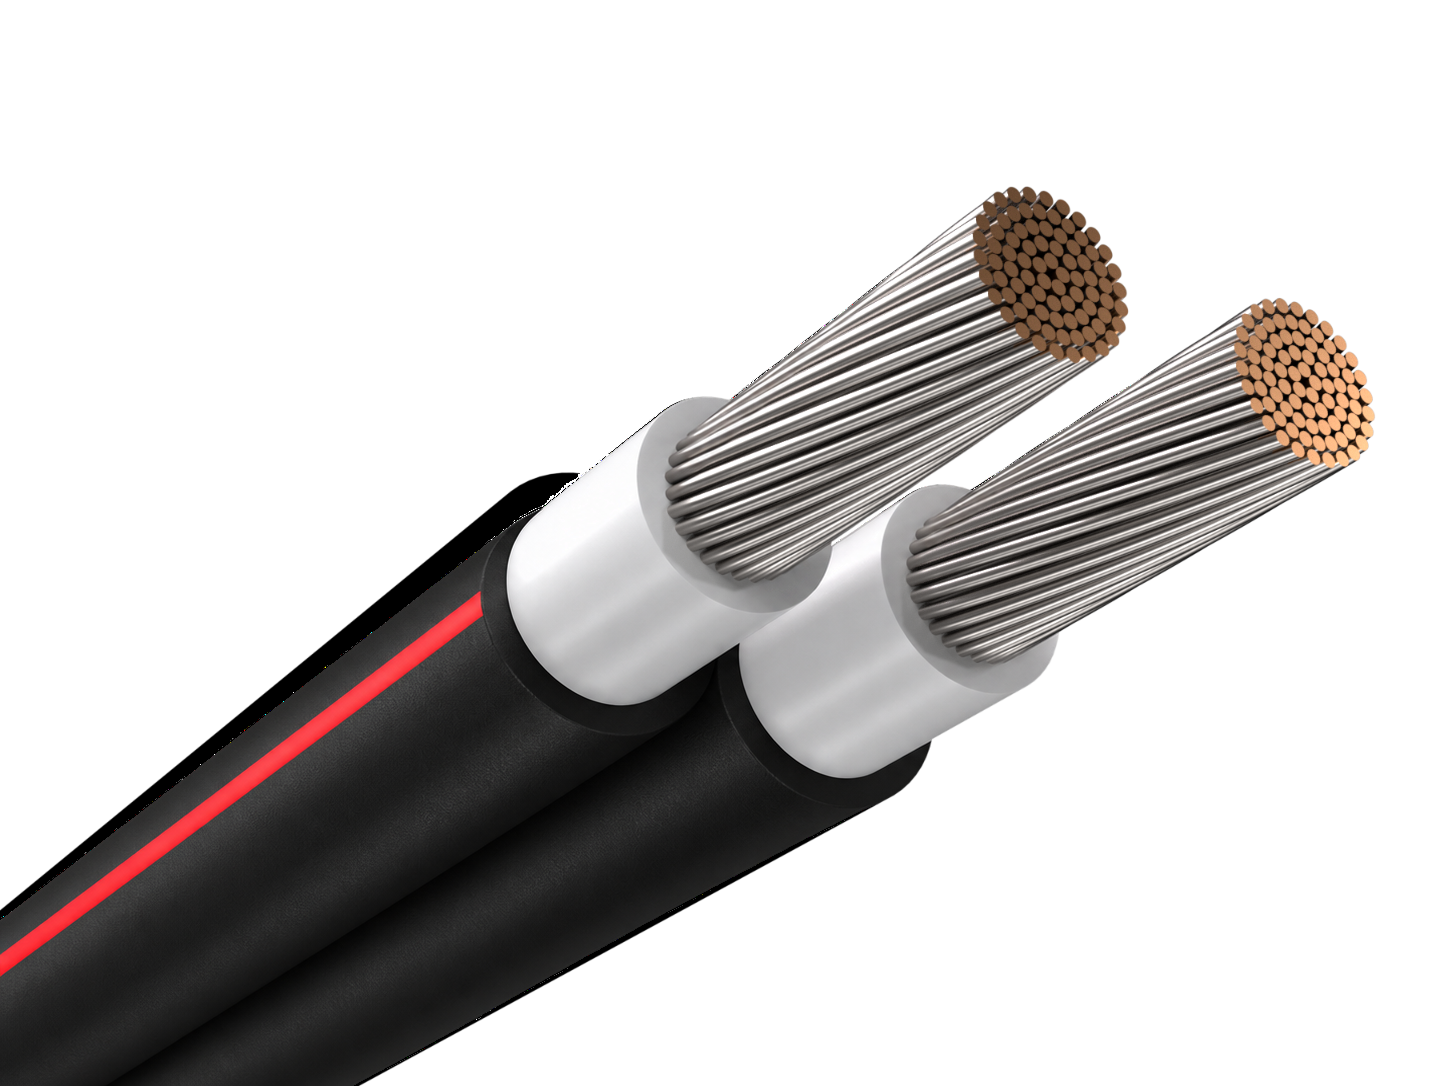
Joined twin PV cable for orderly positive and negative string routing beneath solar modules.
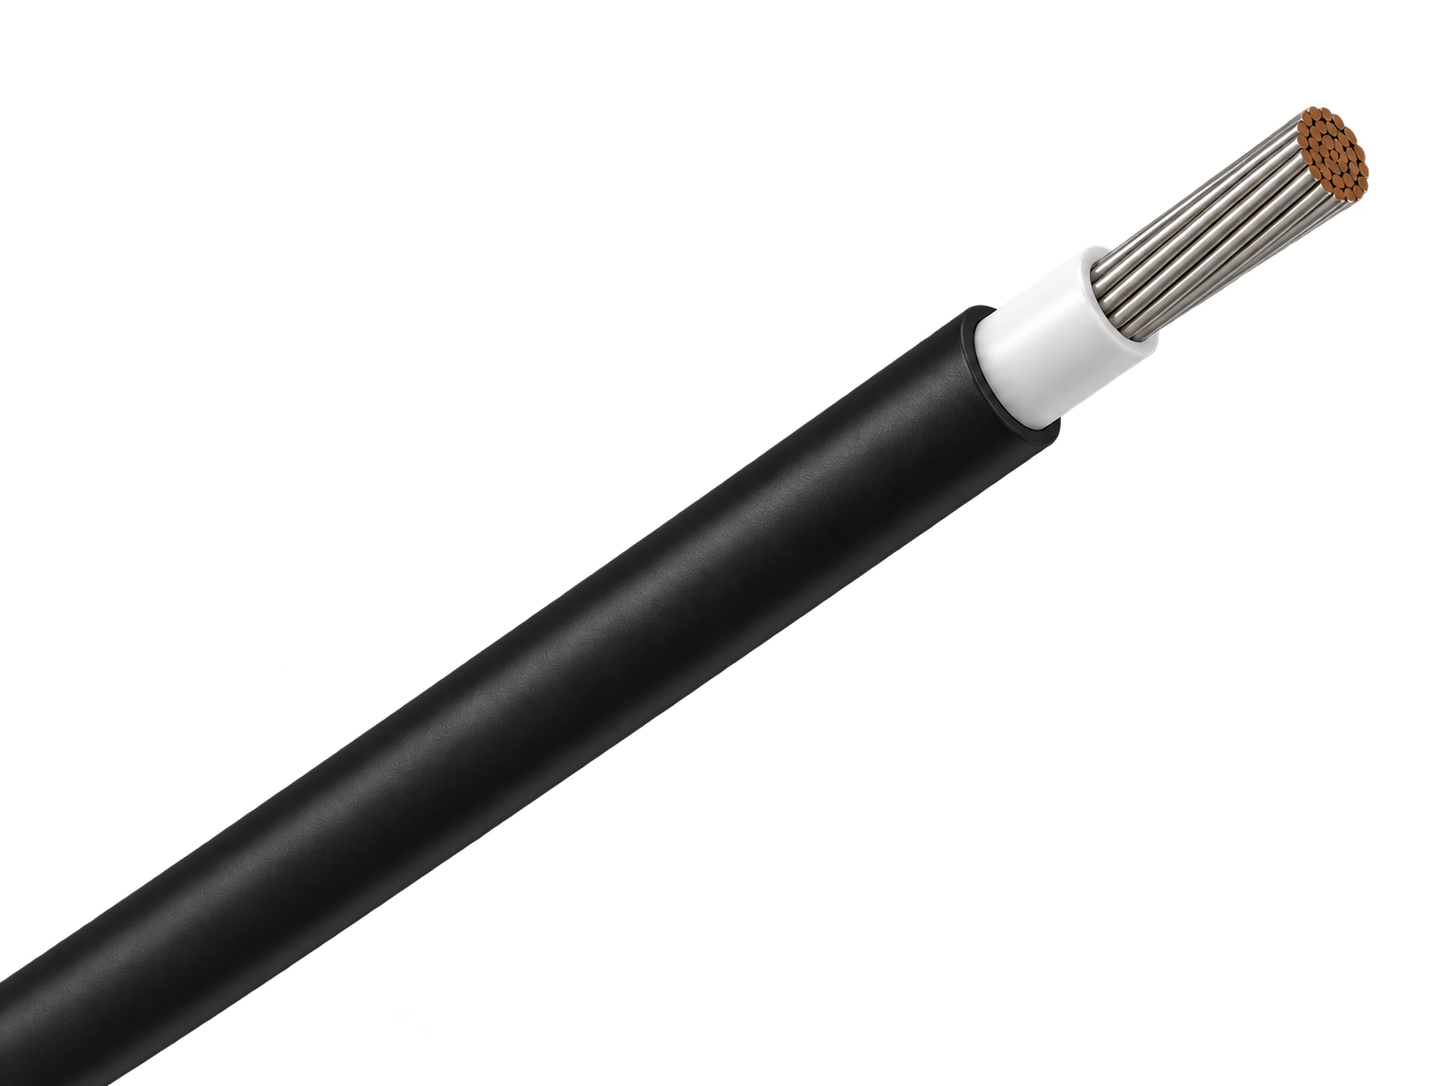
Single-core PV cable for reliable DC wiring across rooftop and ground-mounted solar arrays.
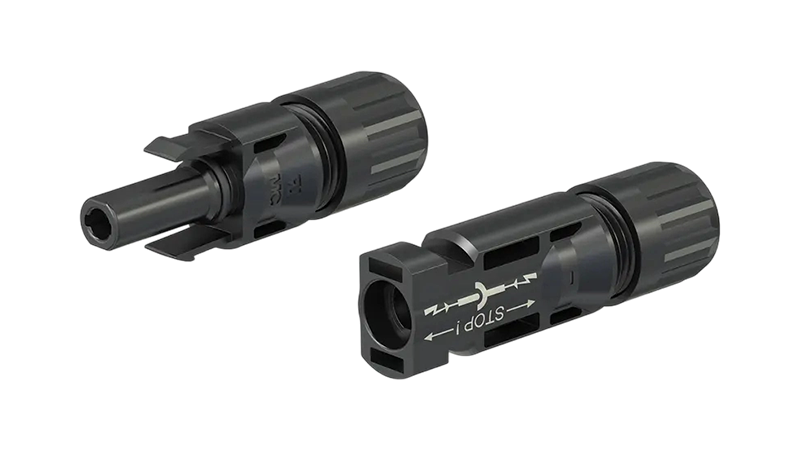
Original 4 mm DC PV connector for field-assembled module, string and extension-cable connections.
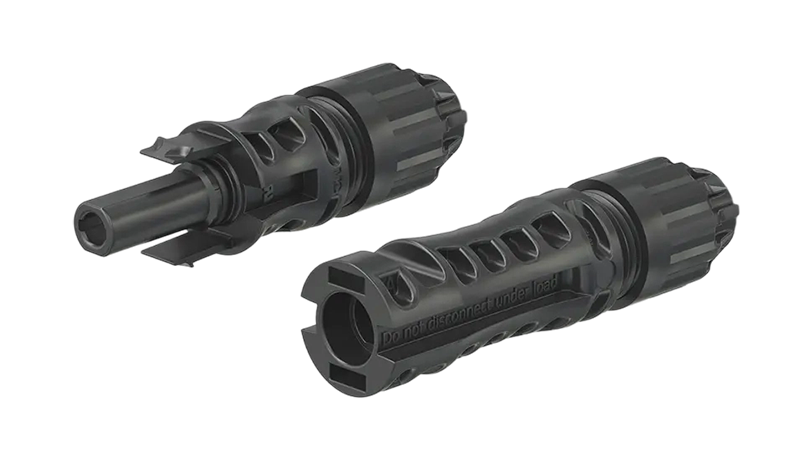
1500 V DC Original Stäubli PV connector for high-current string, extension and equipment connections.
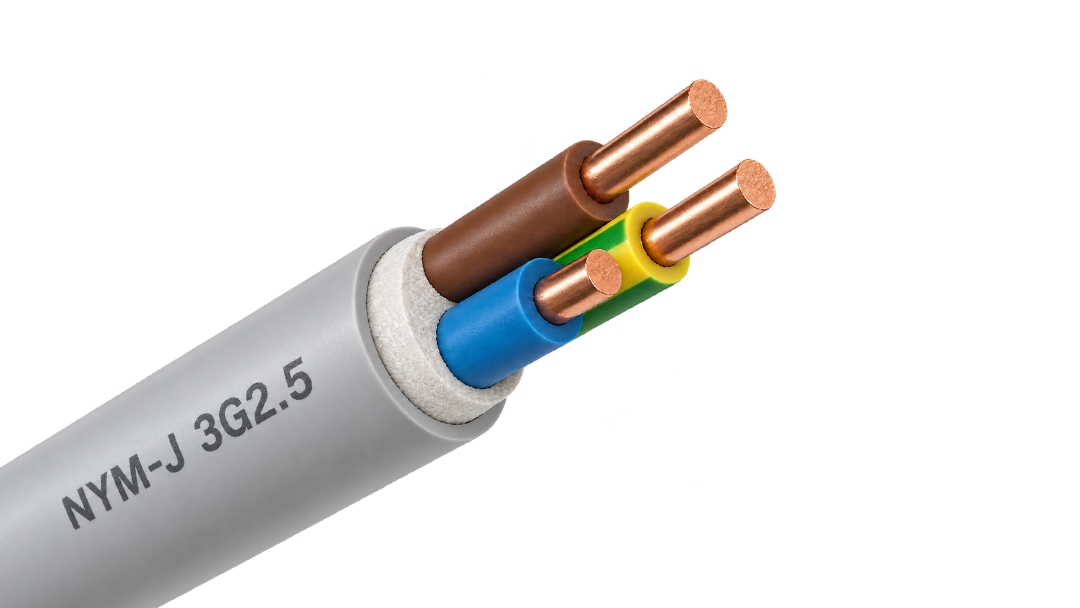
PVC-sheathed 300/500 V cable for fixed power and lighting circuits inside buildings and panels.
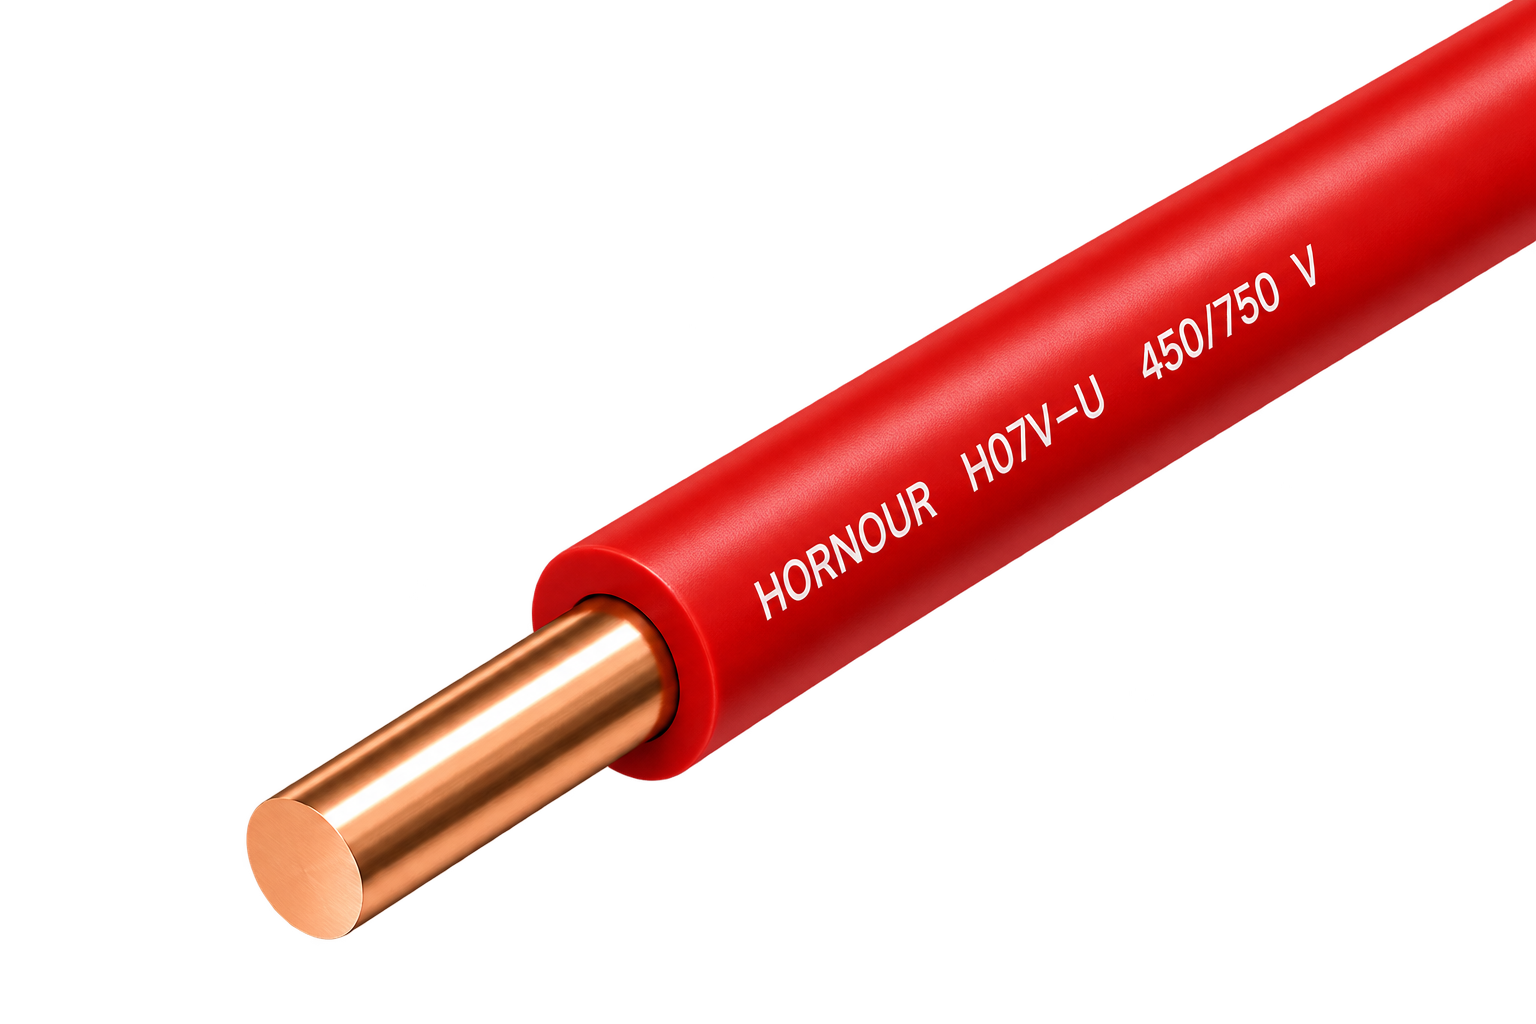
Solid 450/750 V PVC wire for stable fixed circuits in protected conduit and building installations.
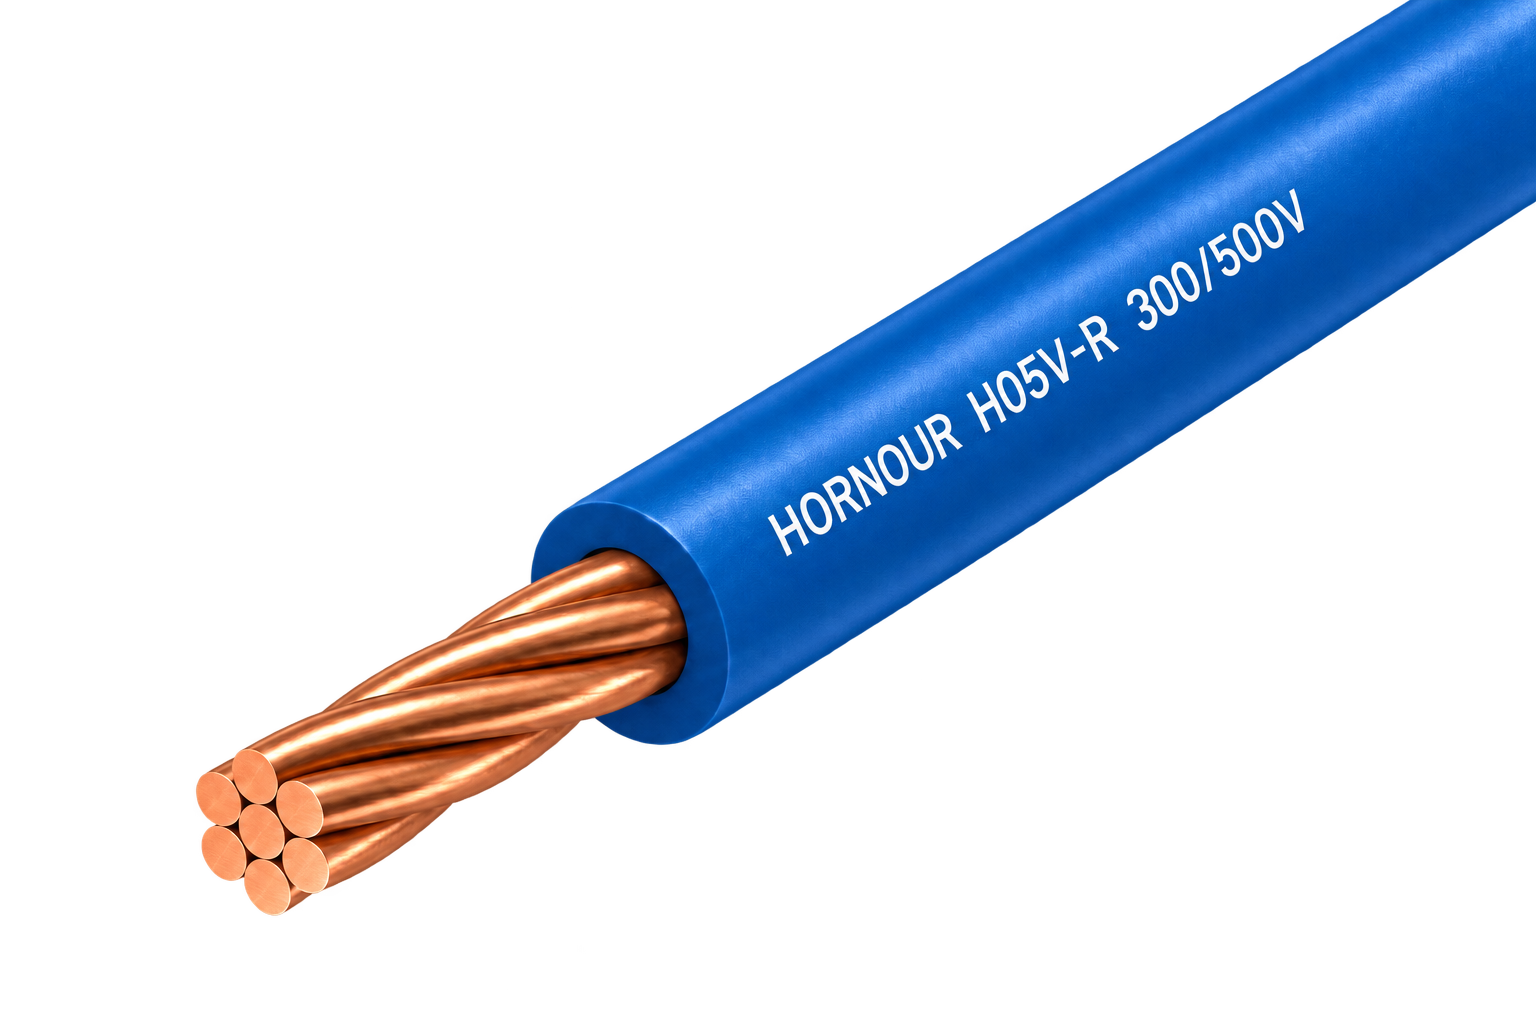
Class 2 stranded 300/500 V PVC wire for fixed equipment and panel routes needing moderate flexibility.
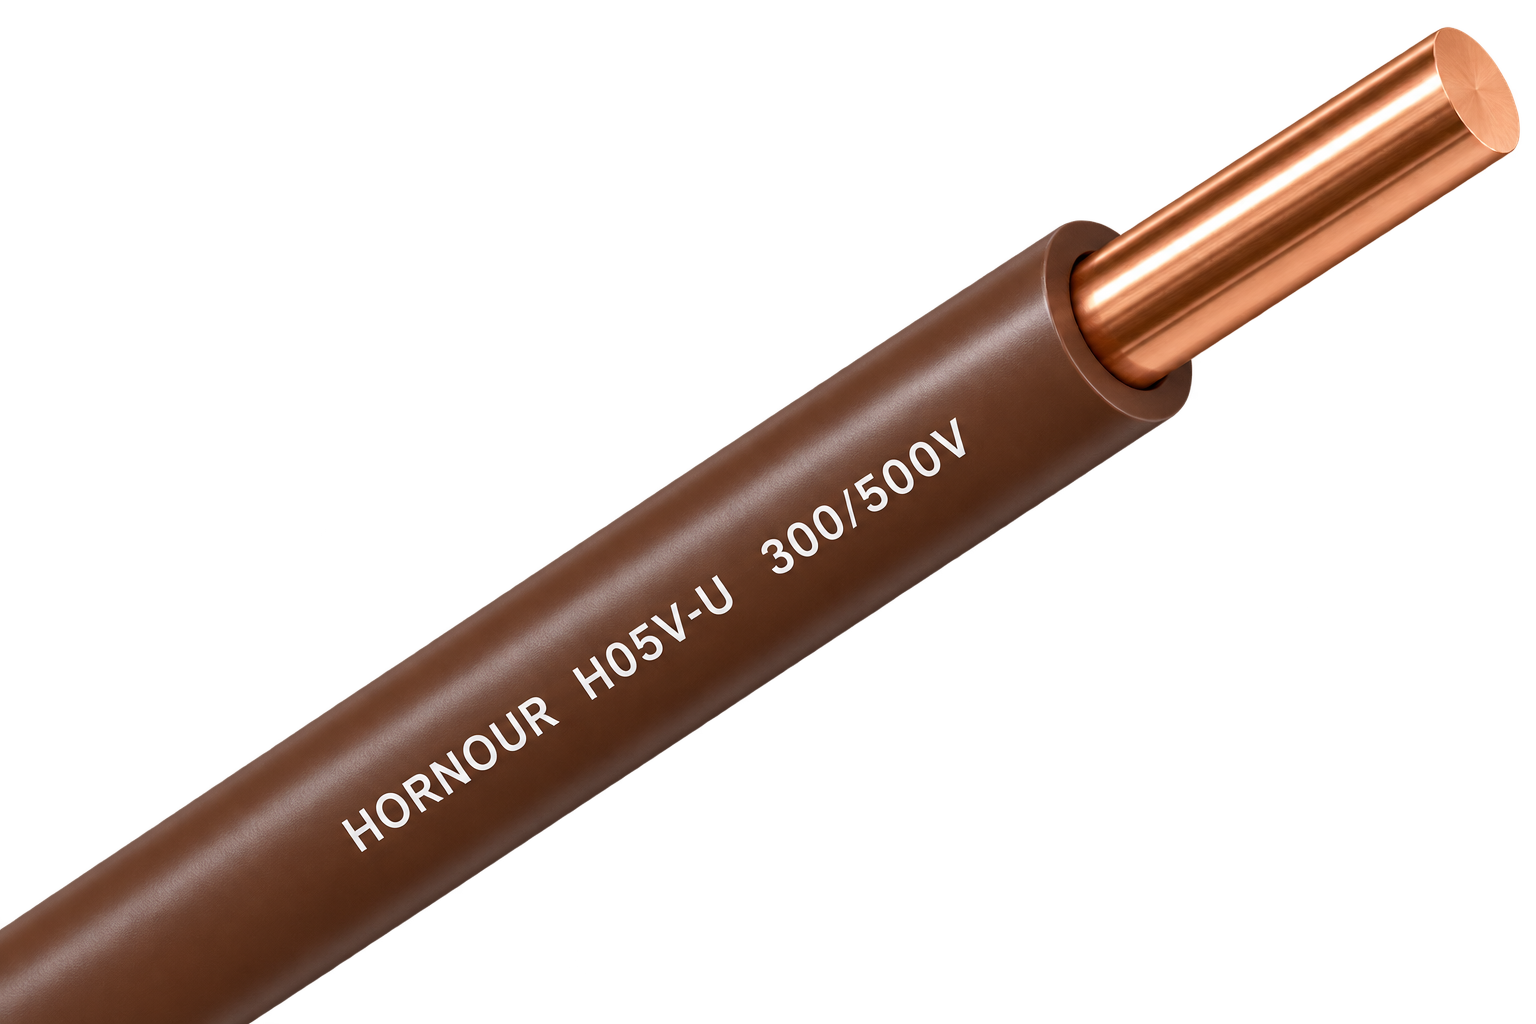
Solid 300/500 V PVC wire for simple, stable fixed connections inside protected equipment and conduit.
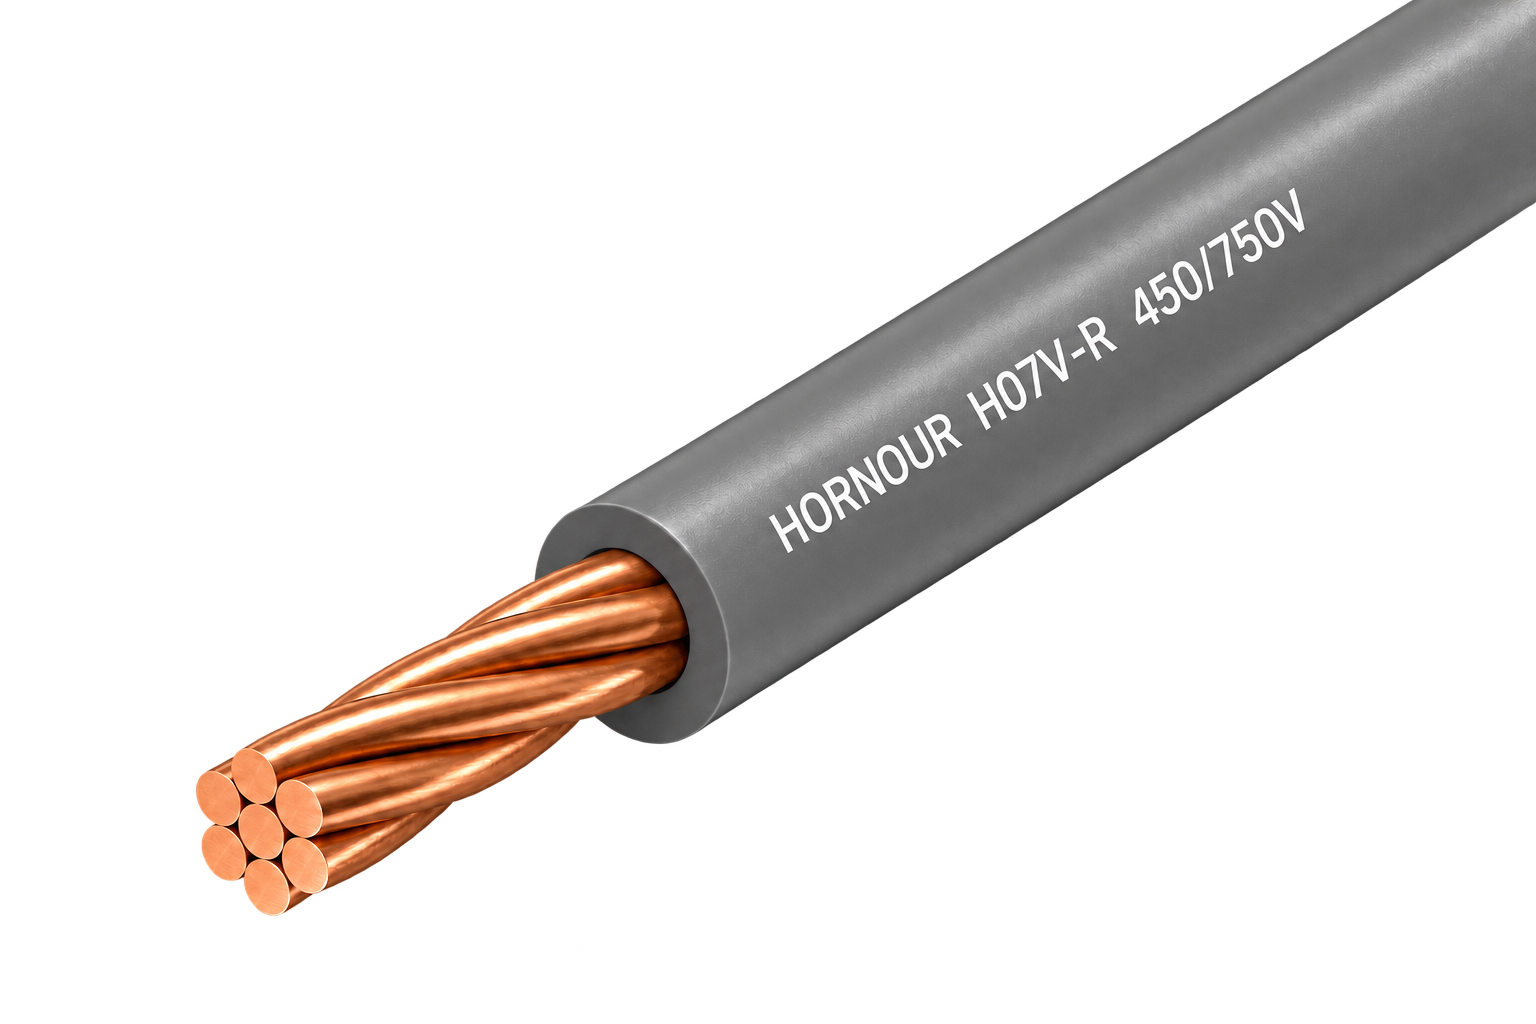
Class 2 stranded 450/750 V PVC wire for protected fixed routes requiring easier pulling and forming.
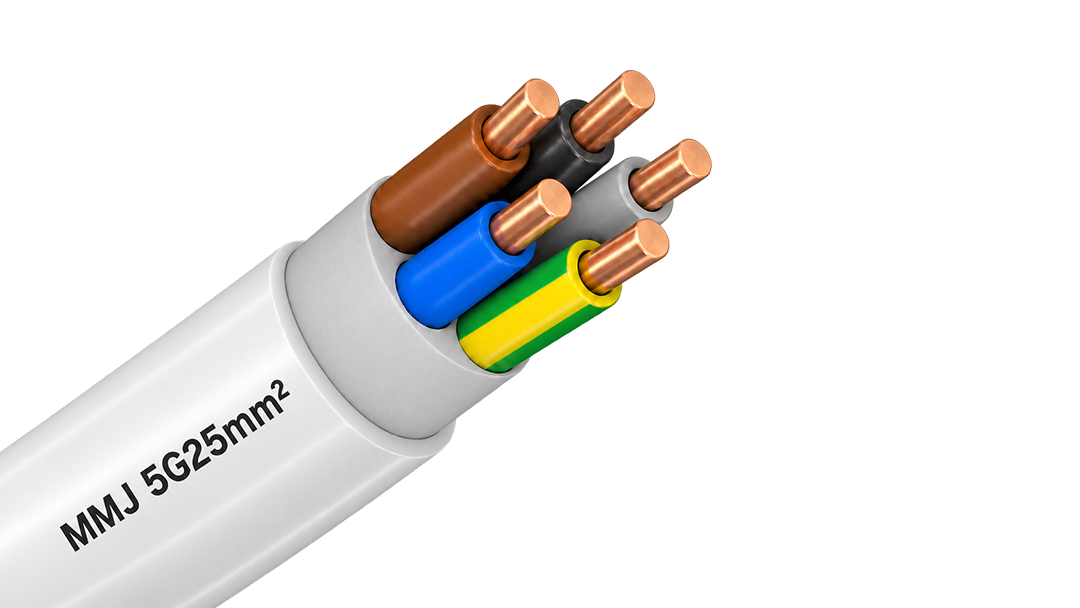
300/500 V PVC-sheathed cable for fixed surface and flush-mounted installations in Finnish building wiring.
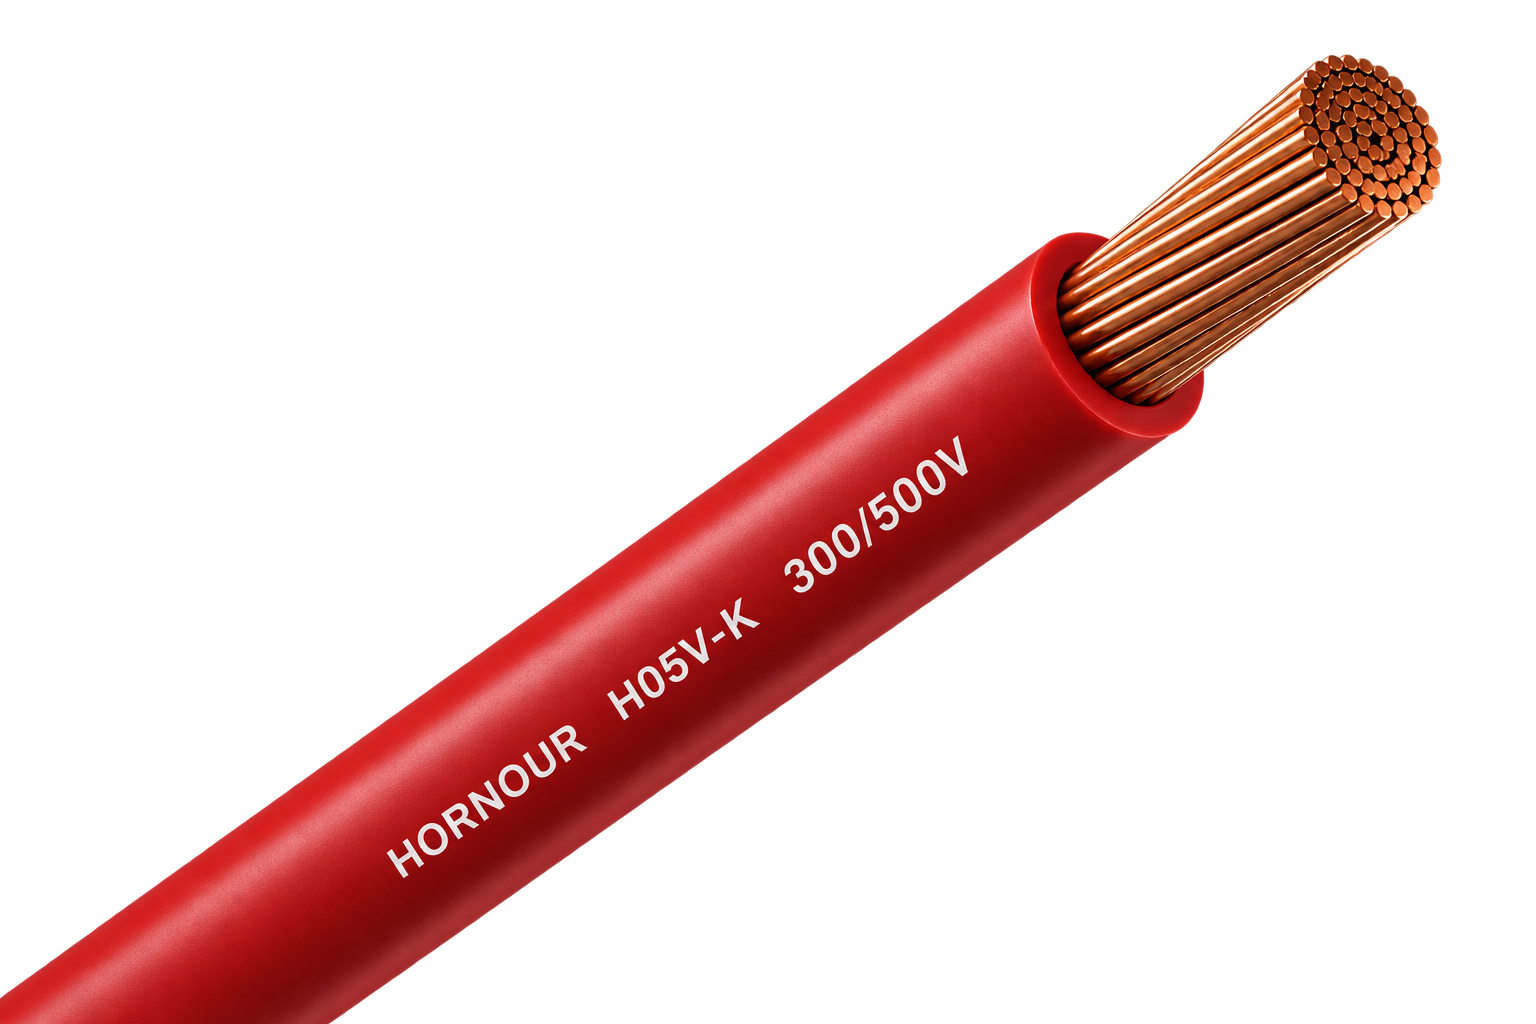
Flexible 300/500 V PVC wire for compact equipment, switchgear and control-panel connections.
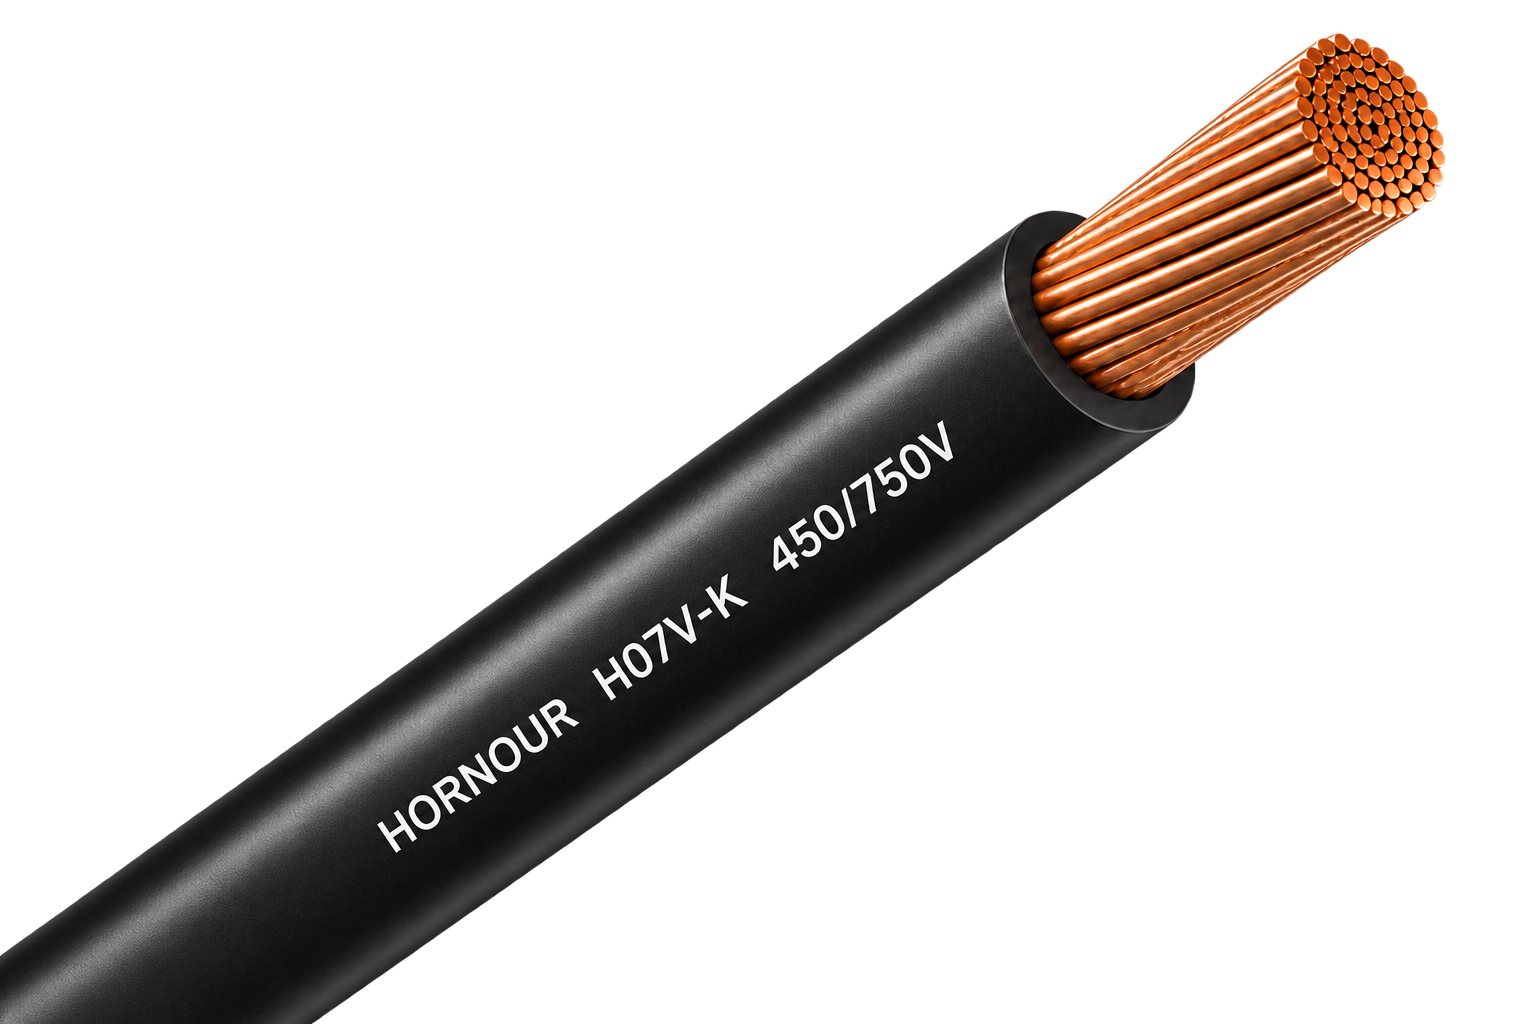
Flexible 450/750 V PVC wire for protected conduit, panel and grounding connections.
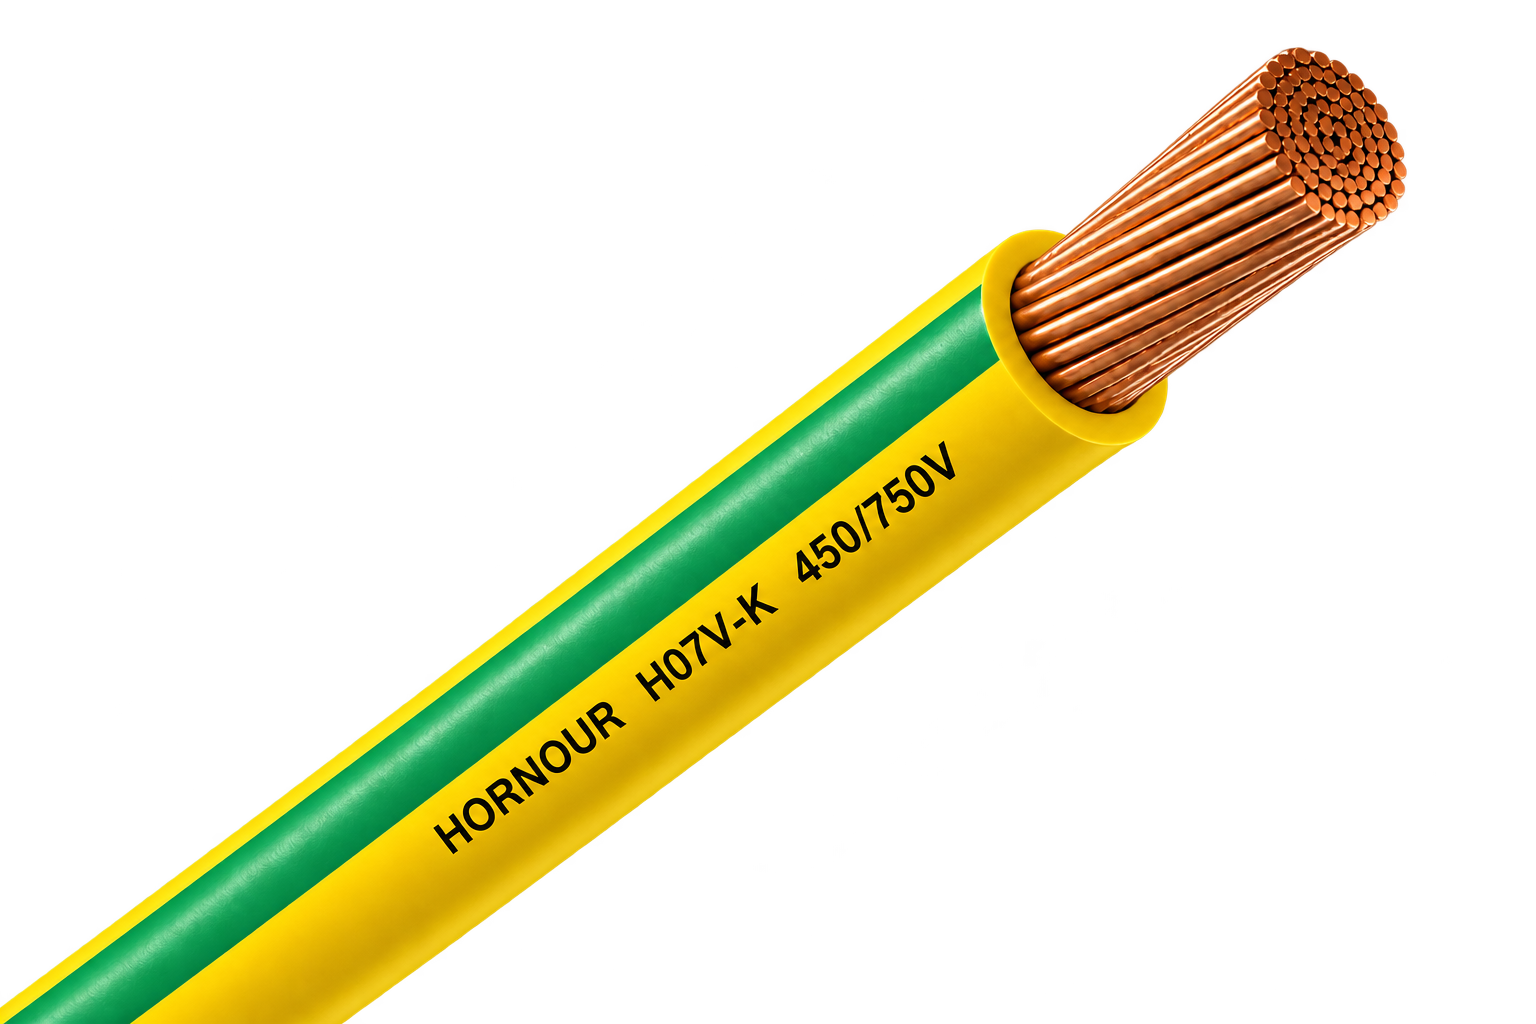
Green/yellow H07V-K Class 5 copper wire for protective-earth and equipotential-bonding connections in PV, ESS and electrical installations.
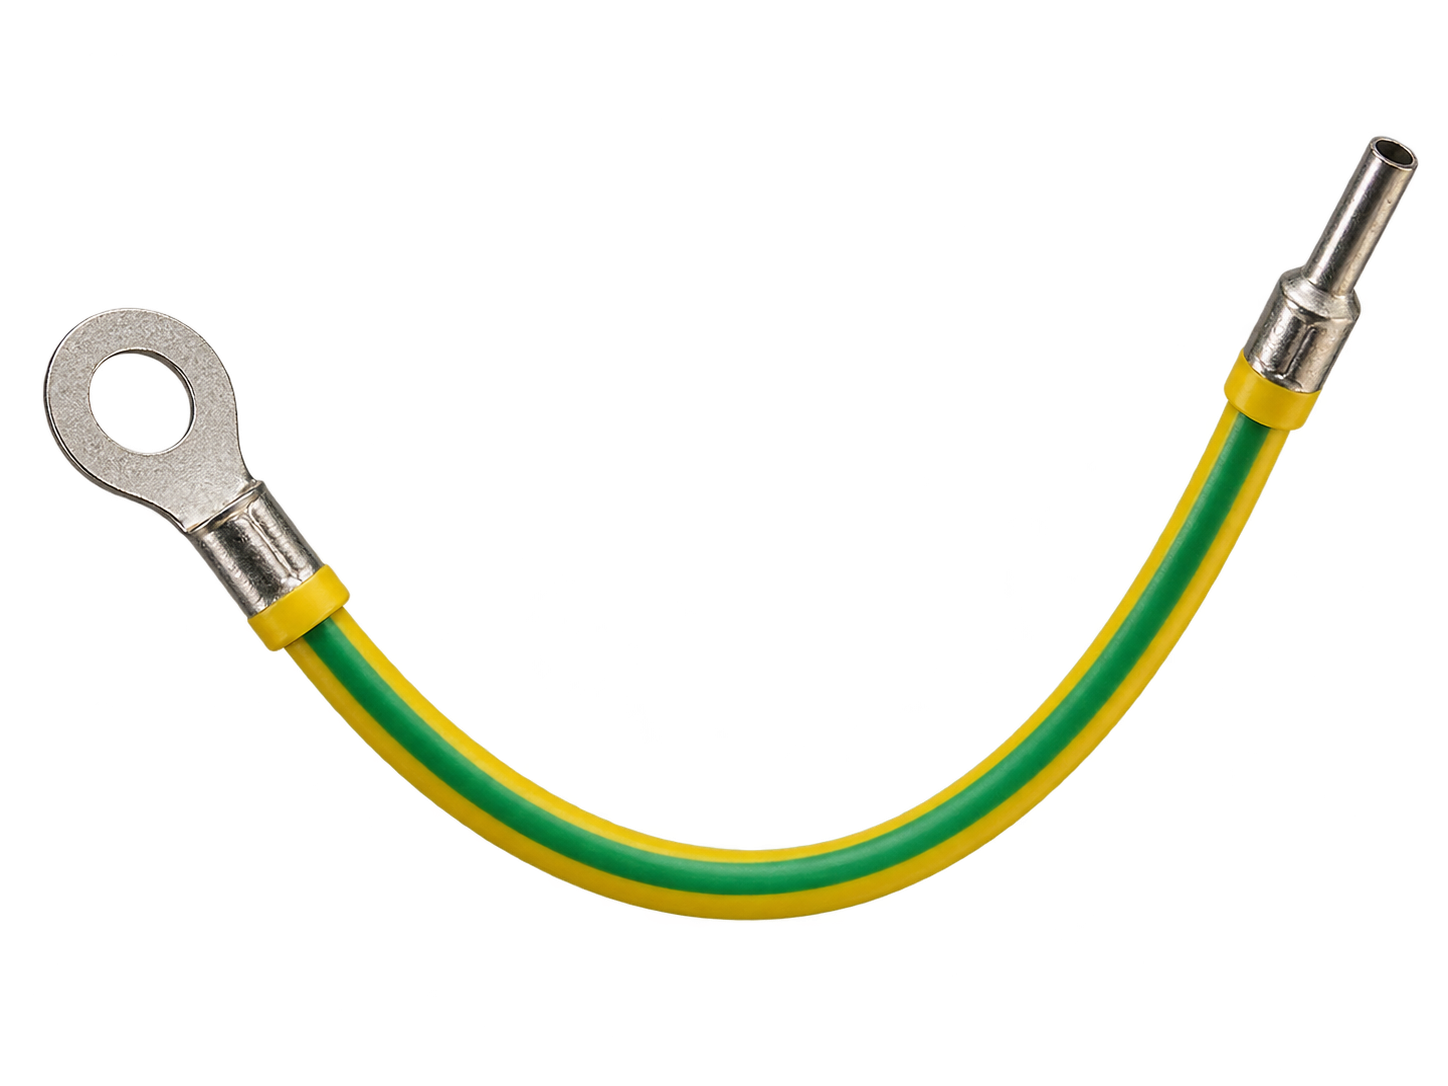
Green/yellow H07V-K grounding lead with factory-crimped ring / OT terminal for ready-to-install earthing and bonding connections.
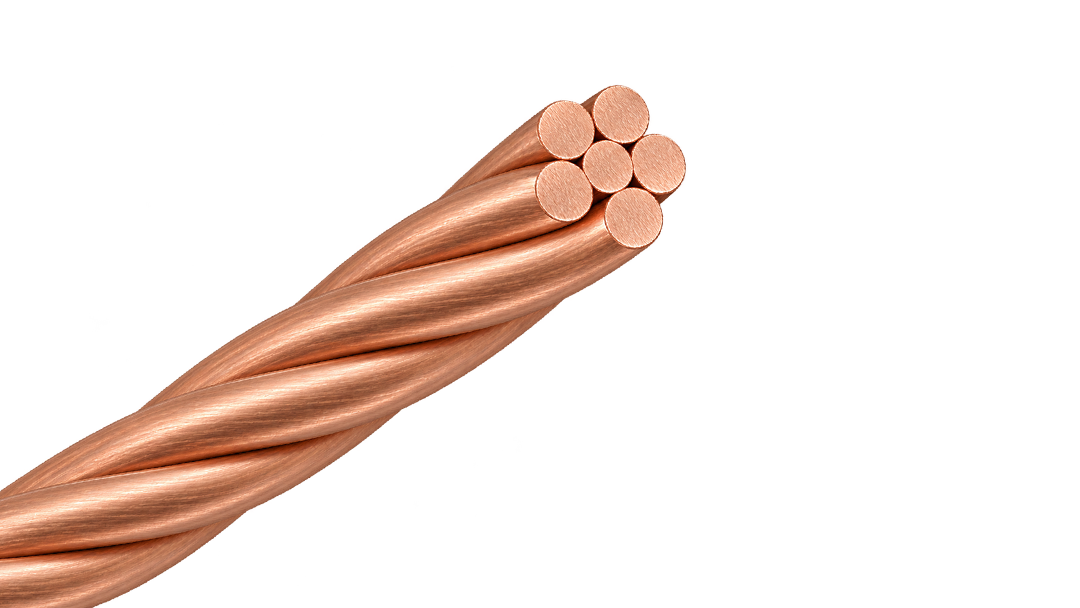
Bare Class 2 stranded copper conductor for earthing and equipotential bonding, available in 16–120 mm².
H1Z2Z2-K 1.5 kV DC solar cable with a nylon barrier beneath the outer sheath for PV routes that need a non-metallic physical defence against rodent damage.
H1Z2Z2-K 1.5 kV DC solar cable with external steel-wire armour for fixed PV routes exposed to severe rodent activity or mechanical damage.
H1Z2Z2-K 1.5 kV DC solar cable with a capsaicin-based rodent-deterrent sheath for PV routes where chemical protection is preferred over added armour.
Factory-terminated PV extension cable for controlled module, string and combiner-box connections.
Joined twin PV cable for orderly positive and negative string routing beneath solar modules.
Single-core PV cable for reliable DC wiring across rooftop and ground-mounted solar arrays.
Green/yellow H07V-K Class 5 copper wire for protective-earth and equipotential-bonding connections in PV, ESS and electrical installations.
Green/yellow H07V-K grounding lead with factory-crimped ring / OT terminal for ready-to-install earthing and bonding connections.
Bare Class 2 stranded copper conductor for earthing and equipotential bonding, available in 16–120 mm².
PVC-sheathed 300/500 V cable for fixed power and lighting circuits inside buildings and panels.
Solid 450/750 V PVC wire for stable fixed circuits in protected conduit and building installations.
Class 2 stranded 300/500 V PVC wire for fixed equipment and panel routes needing moderate flexibility.
Solid 300/500 V PVC wire for simple, stable fixed connections inside protected equipment and conduit.
Class 2 stranded 450/750 V PVC wire for protected fixed routes requiring easier pulling and forming.
300/500 V PVC-sheathed cable for fixed surface and flush-mounted installations in Finnish building wiring.
Flexible 300/500 V PVC wire for compact equipment, switchgear and control-panel connections.
Flexible 450/750 V PVC wire for protected conduit, panel and grounding connections.
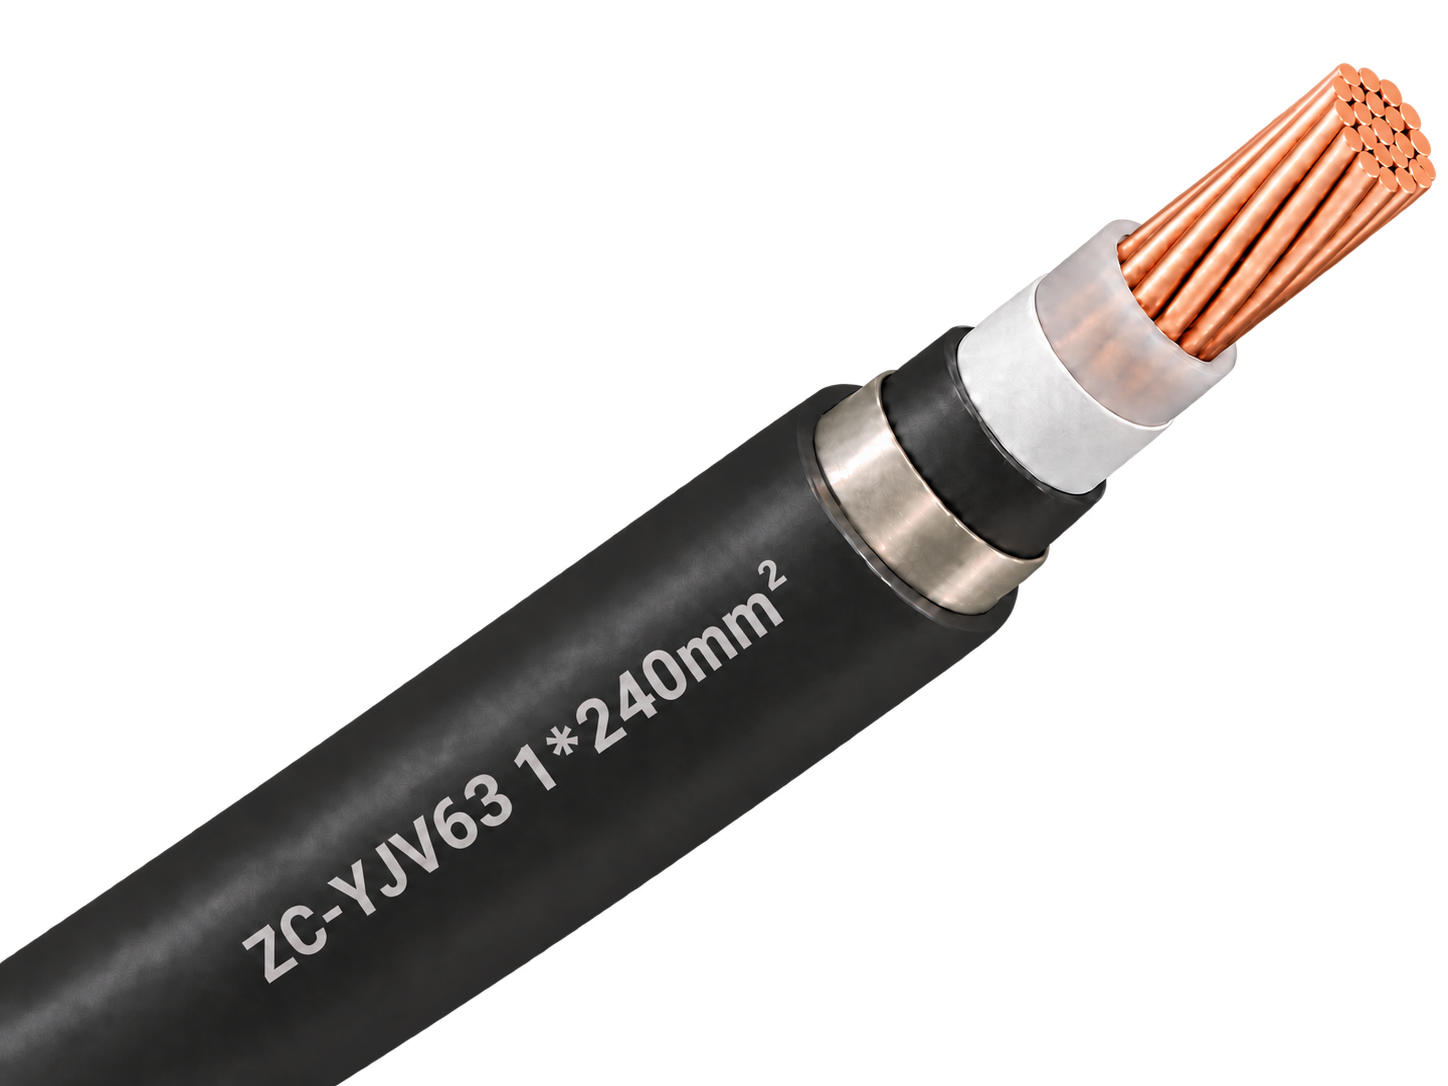
Single-core 1.8/3 kV copper XLPE cable with non-magnetic stainless-steel tape armour, PVC sheath and Category C flame-retardant construction for protected fixed power routes.
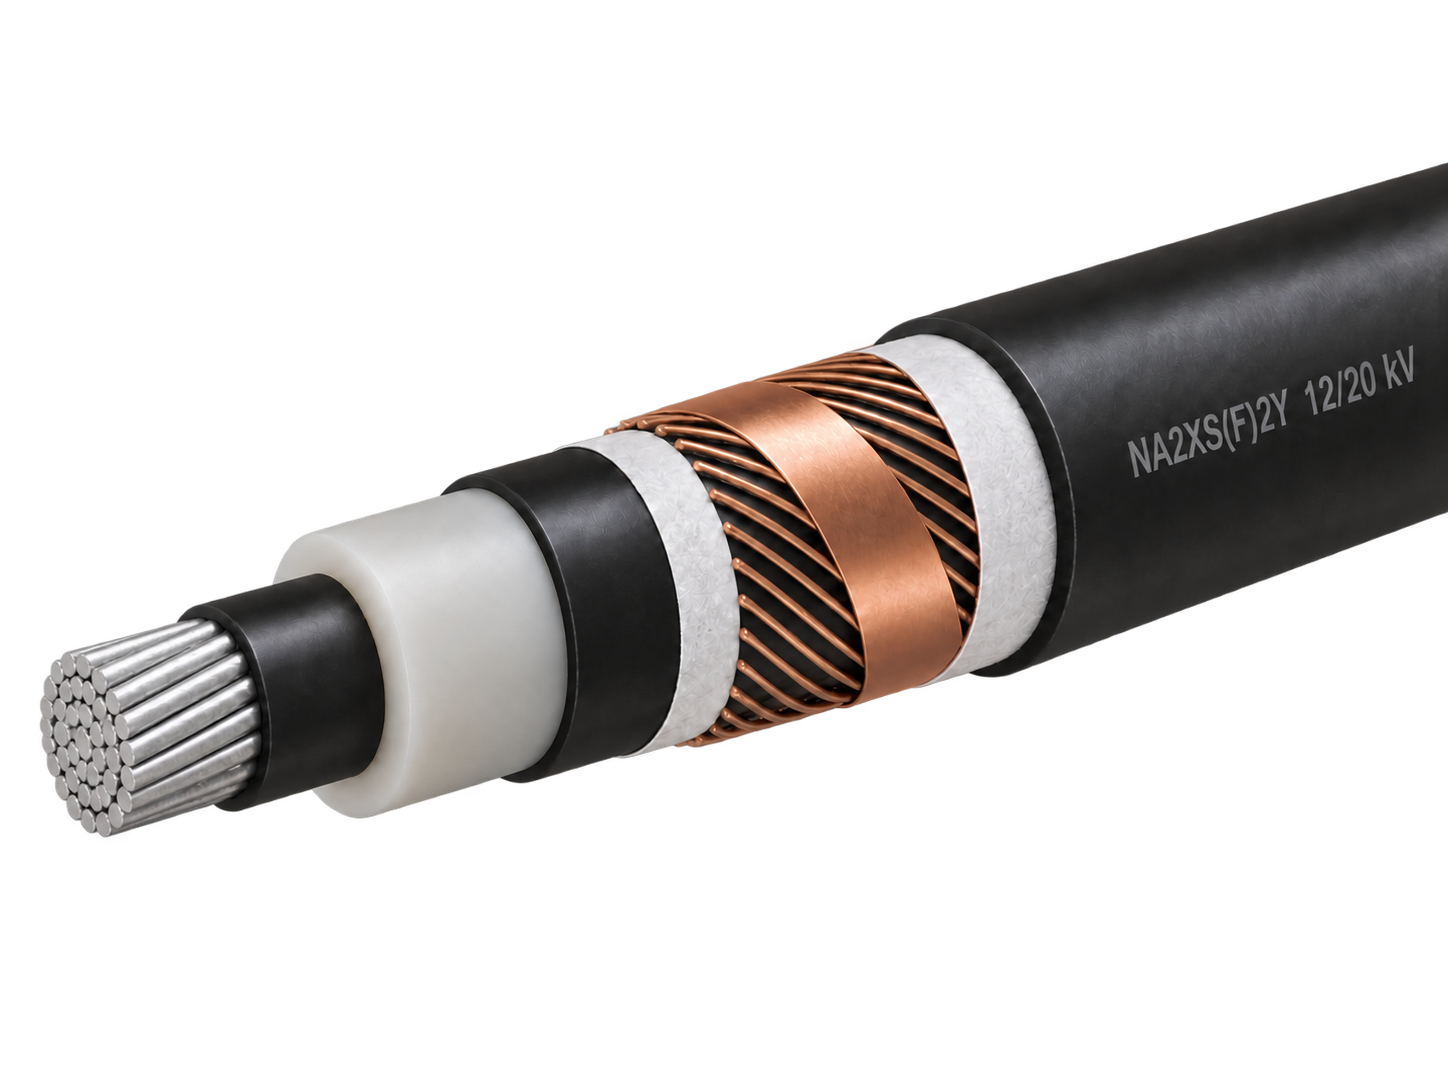
Aluminium XLPE medium-voltage cable with longitudinal water blocking for fixed distribution networks.
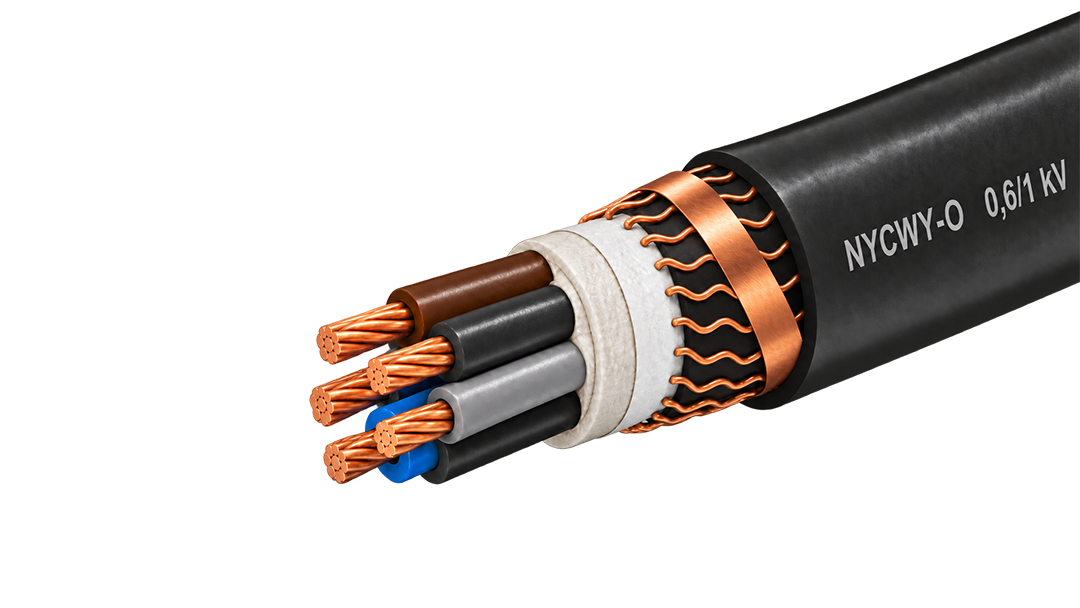
0.6/1 kV copper cable with a wave-laid concentric conductor for fixed distribution and service routes.
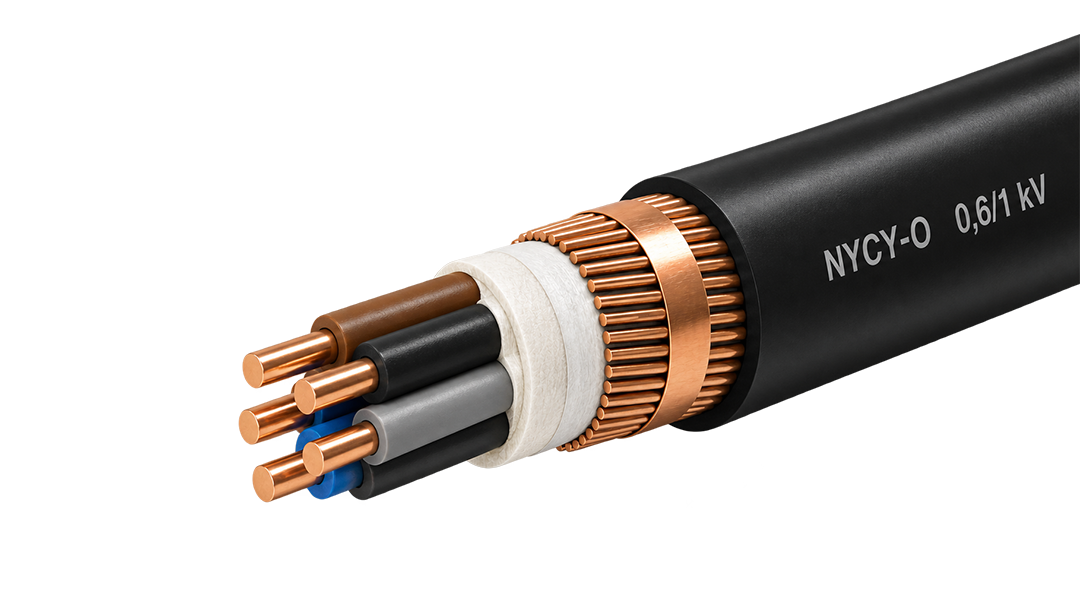
0.6/1 kV copper power cable with a concentric copper layer for service and distribution circuits.
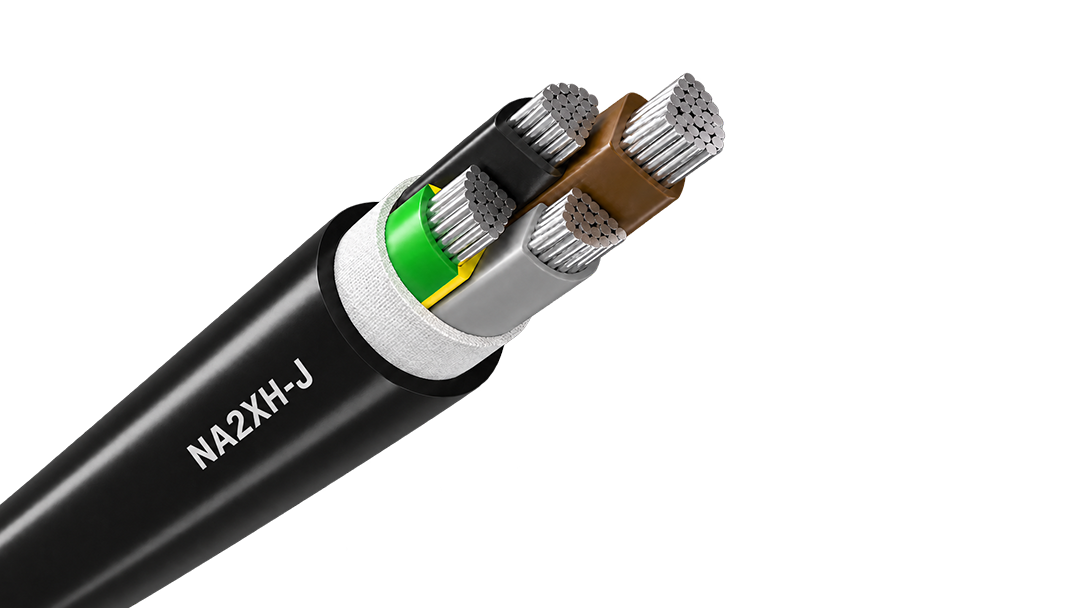
Aluminium halogen-free 0.6/1 kV cable for fire-conscious fixed distribution and long feeders.
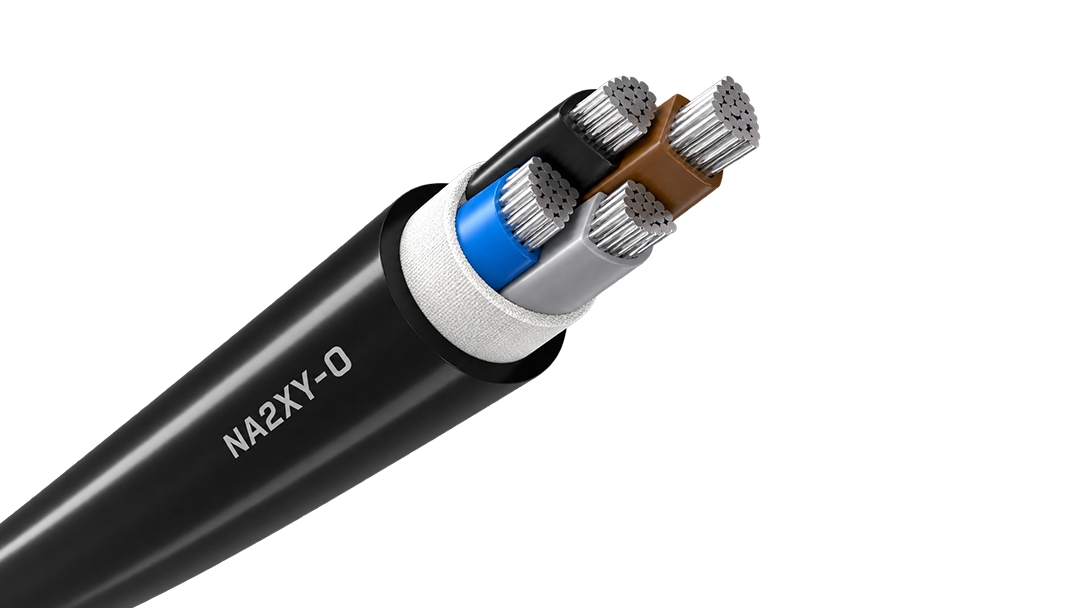
Aluminium XLPE power cable for economical fixed distribution, available in 0.6/1 kV and 1.8/3 kV constructions for long outdoor and buried routes.
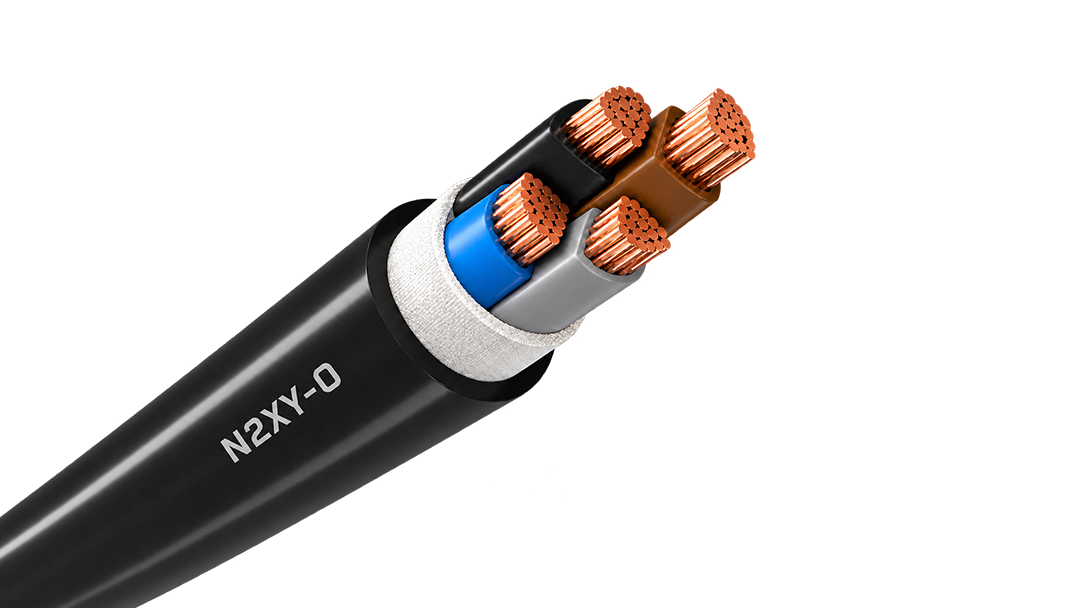
Copper XLPE 0.6/1 kV cable for demanding fixed feeders, outdoor routes and power distribution.
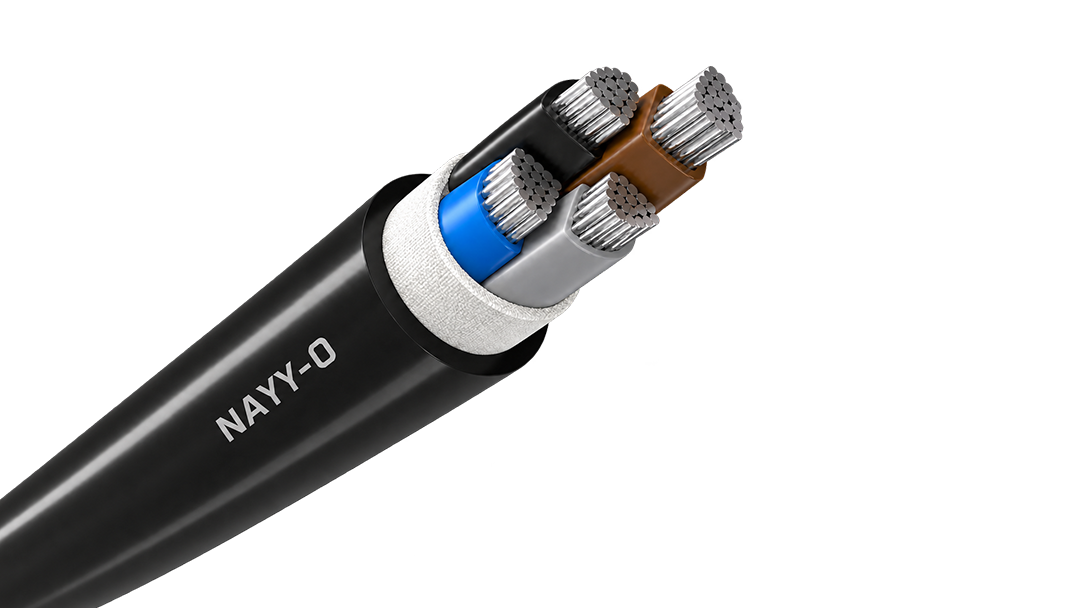
Aluminium 0.6/1 kV PVC cable for cost-conscious fixed distribution and long feeder routes.
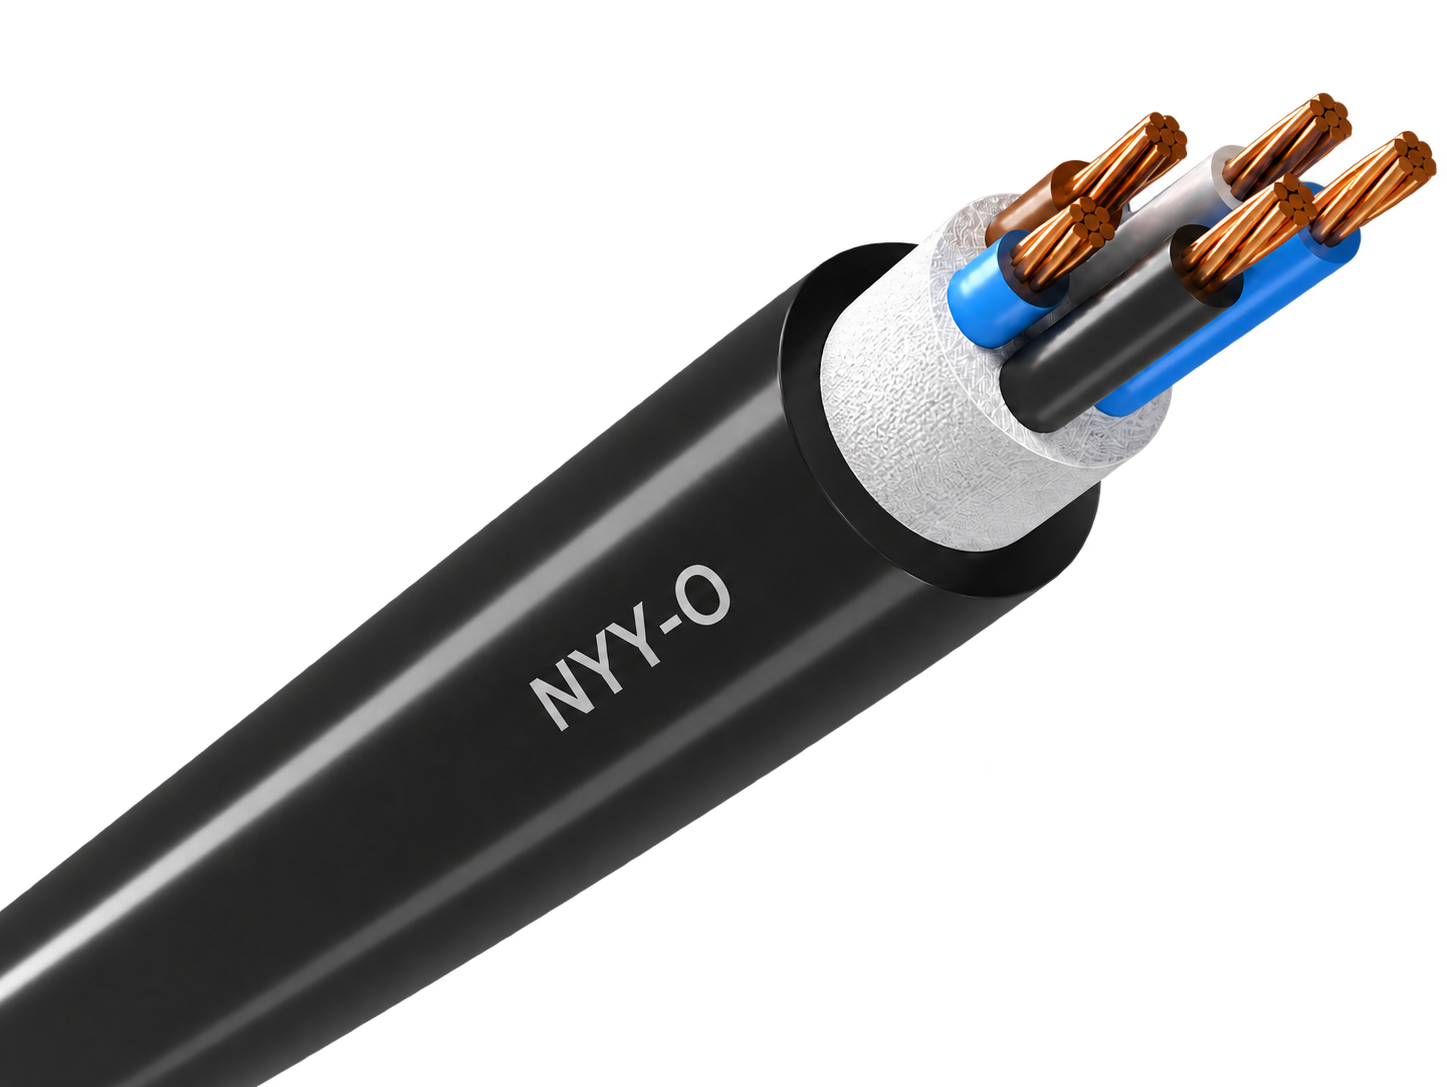
Robust 0.6/1 kV copper cable for economical fixed power distribution indoors, outdoors and underground.
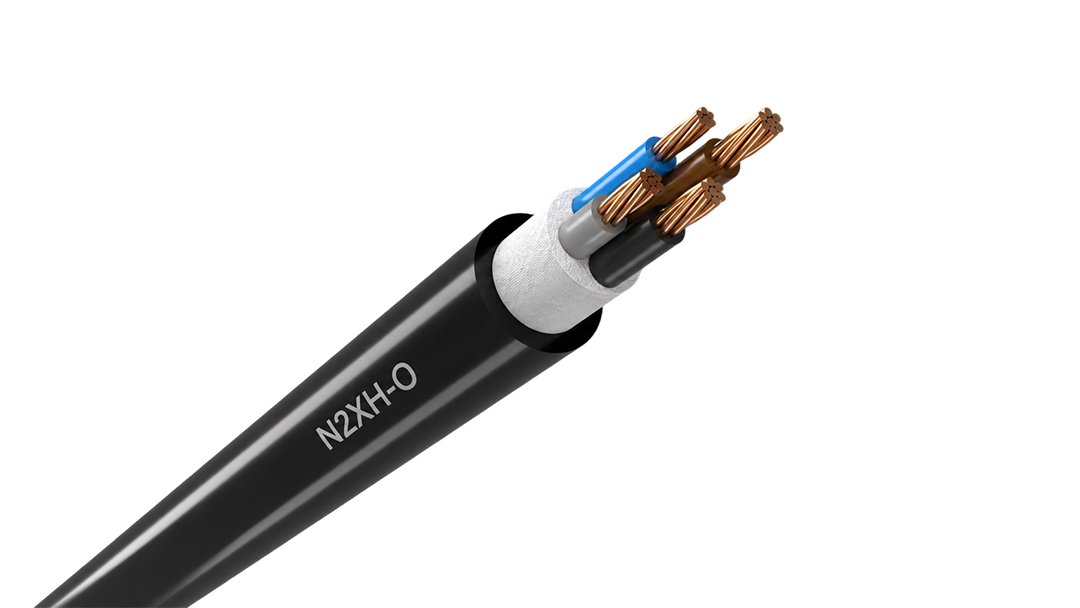
Low-smoke halogen-free 0.6/1 kV cable for fixed distribution in occupied and critical buildings.

hot search


Spain’s Ministry for the Ecological Transition has published the draft tender for the Maciñeira 400 kV grid node, where 600 MW of grid connection capacity is expected to be allocated to new renewable energy and storage projects.
The public consultation will remain open until 22 October.
Unlike broader grid-access consultations, the Maciñeira process already identifies a specific node, available capacity and evaluation framework. The tender will consider factors including local employment, training, self-consumption and industrial investment, while projects incorporating energy storage, grid-support capabilities and greater development maturity are expected to receive stronger consideration.
This makes the tender more relevant to the project supply chain than a general capacity announcement.
If successful projects progress toward construction, demand could eventually extend across several cable categories, including PV DC cables, ESS DC cables, earthing cables, LV power cables between PCS and transformers, and MV cables within substations.
However, the 600 MW figure should not yet be treated as immediate procurement volume. The more important next step is identifying the developers, BESS integrators and EPC contractors participating in the tender and following which projects actually secure grid access.
For cable manufacturers and project suppliers, Spain therefore represents a pipeline-development opportunity rather than a short-term inventory signal.
Germany’s third 2026 auction for solar installations on buildings and noise barriers closed on 1 October, with an auction volume of 296.269 MW and a maximum bid price of €0.10/kWh.
Under Solarpaket I, Germany had planned to expand the 2026 rooftop PV auction volume and reduce the minimum eligible project size to 751 kW.
Those changes have not yet received the required EU state-aid approval. As a result, the October auction continues under the previous framework, with the minimum project size remaining at 1.001 MW.
The delay does not indicate that Germany’s commercial and industrial rooftop solar market is disappearing. It does, however, show that longer-term policy ambitions have not yet fully translated into near-term auction-supported project volume.
For suppliers of solar cables and PV DC cables, the practical market signal will therefore come from the final award results rather than the headline annual target.
Winning developers, EPC contractors and project sizes will provide a more reliable indication of actual cable procurement opportunities than Germany’s nominal 2.3 GW annual auction target alone.
Italian transmission system operator Terna has published the results of its procurement for the Q4 2026 upward instantaneous extraordinary modulation service, covering the period from 1 October to 31 December.
The mechanism provides an additional revenue opportunity for battery storage and other fast-response flexible resources participating in the Italian electricity system.
For BESS projects that are already connected or approaching commercial operation, access to flexibility and ancillary-service revenues can strengthen operating economics and improve the overall business case for storage assets.
From a cable-market perspective, however, this distinction is important.
The Q4 procurement is an operating-service auction, not a new BESS capacity auction. It should therefore not be interpreted directly as new demand for ESS DC cables, LV power cables or MV cables.
The stronger commercial signal lies in identifying storage operators with established revenue streams and then monitoring whether those companies move into Phase II expansion, repowering, equipment replacement or additional BESS projects.
The clearest new project-development signal this week comes from Spain. The Maciñeira 600 MW tender has progressed beyond a broad policy announcement and now provides a defined grid node and project evaluation process.
Germany remains an important rooftop PV market, but the latest auction confirms that regulatory implementation can still delay the conversion of policy targets into actual projects.
Italy, meanwhile, continues to develop the revenue environment required to support operating battery storage assets, although the latest flexibility procurement does not itself represent new construction capacity.
For suppliers of PV DC cables, ESS DC cables, earthing cables and LV/MV power cables, the key distinction remains the same: announced capacity, auctioned capacity and actual procurement demand are not interchangeable.
Project maturity, EPC selection, financing and construction schedules remain the more reliable indicators of near-term cable demand.
HORNOUR supplies cable solutions for solar PV, battery energy storage and power infrastructure projects, including PV DC, ESS DC, LV and MV cable applications.
Explore HORNOUR cable solutions for PV, ESS and power projects
Spain: the 600 MW Maciñeira tender is a meaningful new PV + BESS project lead, but procurement will depend on final allocation and project execution.
Germany: rooftop solar continues to develop, although the October auction remains constrained by delayed state-aid approval.
Italy: Q4 flexibility procurement supports BESS operating revenues but should not yet be treated as evidence of new cable demand.
No major changes were identified this week affecting existing European market-access requirements for PV DC, ESS DC, installation, LV or MV cables under CPR, CE, RoHS or REACH.